
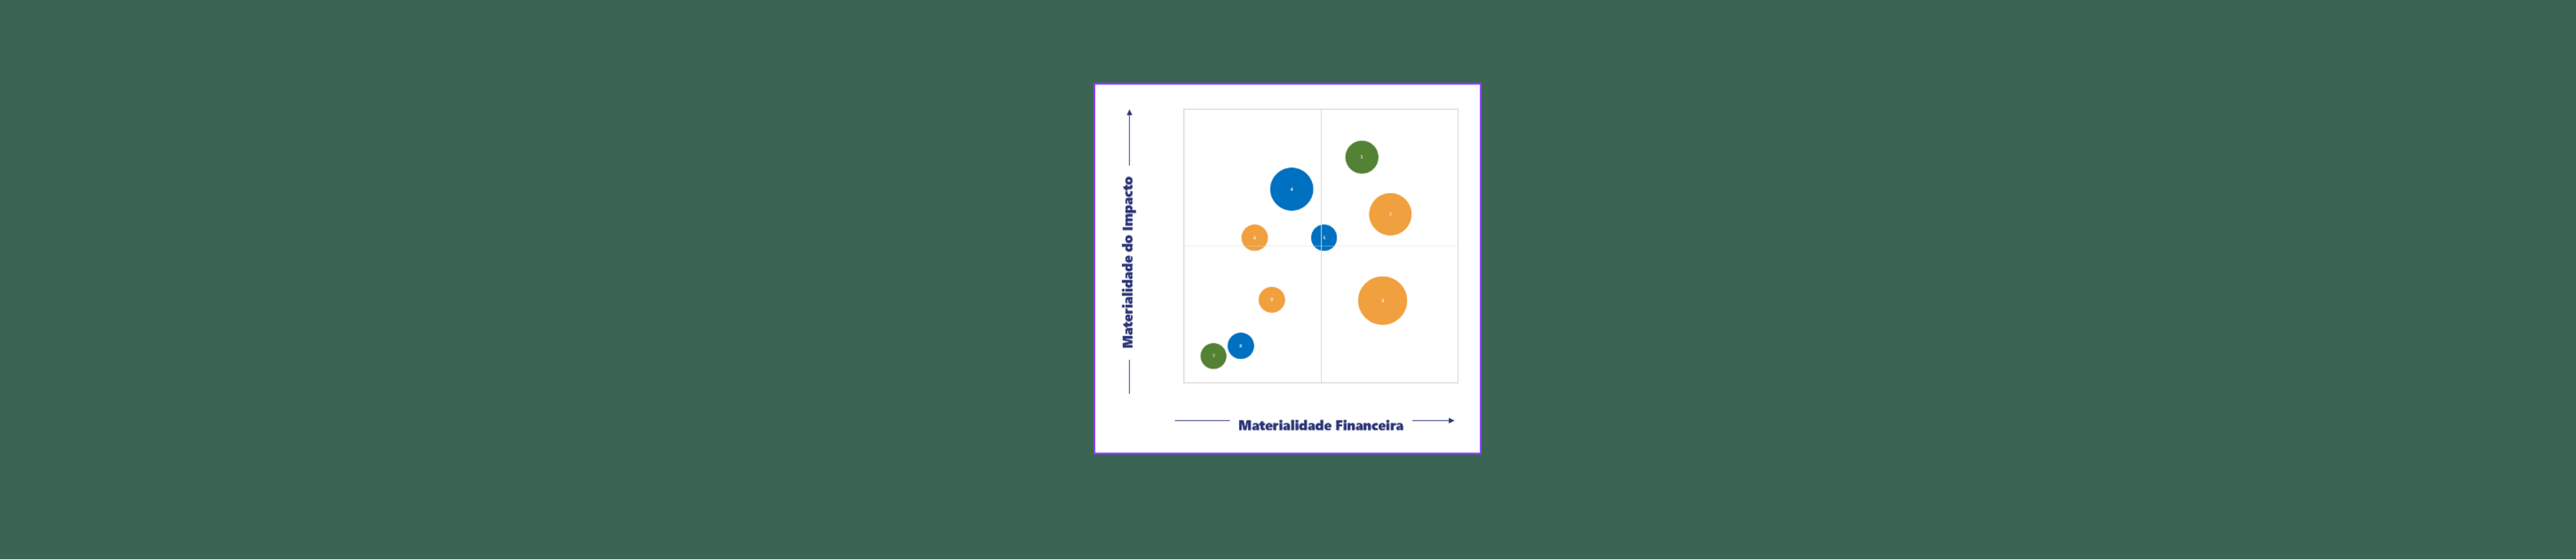
Double Materiality has gained prominence as an essential concept for companies and investors, guiding the prioritization of strategic topics and transparency in corporate reporting.
Over time, the way materiality is understood and applied has evolved, expanding the focus from financial impact to also include the social and environmental impacts generated by companies.
What is Materiality, and Why is Double Materiality Gaining Attention?
Traditionally, materiality assessments have focused on financial materiality, which examines how environmental, social, and governance (ESG) issues impact a company from an economic standpoint.
This approach is adopted by standards such as the SASB (Sustainability Accounting Standards Board) and IFRS S1 and S2, published by the International Sustainability Standards Board (ISSB).
From this perspective, a topic is considered material if it can significantly influence the company’s financial position, either through risks or opportunities.
On the other hand, impact materiality shifts this focus by considering the company’s effects on society and the environment.
This perspective is widely adopted by frameworks such as the GRI Standards (Global Reporting Initiative), which encourage companies to report information relevant to their stakeholders, even if it does not have a direct short-term financial impact.
Double Materiality emerges as a concept that combines both perspectives: financial materiality and impact materiality.
It is a core requirement for companies subject to the Corporate Sustainability Reporting Directive (CSRD) of the European Union and is also present in emerging regulations worldwide.
The double materiality approach acknowledges that certain topics may be relevant to a company both for their influence on financial performance and for their social and environmental impacts.
This paradigm shift challenges companies to adopt a broader view of materiality, linking their business strategy to societal expectations and new regulatory requirements. But how can this approach be effectively implemented in practice?
Double Materiality in Practice: How to Identify Impacts and Risks?
Implementing Double Materiality in practice requires a structured approach to identify both the financial impacts of ESG issues on the company and the impacts the company generates on society and the environment.
According to ABNT PR 2030-2: Guidelines for Determining Materiality, these are the 10 necessary steps:
- Understand the organization’s context
- Map stakeholders
- Identify impacts
- Assess the significance of impacts
- Identify potentially material topics
- Consolidate the organization’s perspective
- Engage with stakeholders
- Build the materiality matrix and prioritize topics
- Conduct strategic analysis
- Validate material topics and finalize the list
Step-by-Step Guide to ABNT PR 2030-2: Guidelines for Determining Materiality
If you want to fully understand ABNT PR 2030-1, which serves as a solid foundation for the concepts used in PR 2030-2, I highly recommend this summary I wrote—it provides a clear and practical overview of everything covered in the standard.
Now, let me show you what you can do in each of these 10 steps:
1. Understand the Organization’s Context
Before conducting a Double Materiality analysis, it is essential to understand the industry, business model, value chain, and regulatory and market challenges the company faces. This context helps define which factors are most relevant in assessing impacts and risks.
2. Map Stakeholders
Identifying key stakeholders—such as customers, investors, regulators, suppliers, and communities—ensures that diverse perspectives are considered in the materiality process. Each group may have different perceptions of the impacts and risks associated with the company.
3. Identify Impacts
The company must map positive and negative, real and potential impacts that its operations, products, and services generate in society and the environment. This analysis should consider both financial materiality and impact materiality.
A practical way to do this is by analyzing the value chain and the activities carried out by the organization.
4. Assess the Significance of Impacts
Not all impacts have the same relevance. Four key variables help determine priority issues that require greater management attention:
- Probability
- Scope
- Intensity
- Urgency/Opportunity
5. Identify Potentially Material Topics
Based on the impact and risk analysis, potentially material topics are identified. These topics should reflect stakeholder demands, regulatory trends, and market expectations.
At this stage, it is useful to group similar risks under overarching “umbrella themes.”
6. Consolidate the Organization’s Perspective
The company’s internal perspective on material topics needs to be structured to ensure alignment between strategic and operational areas with the materiality analysis conducted so far.
7. Engage with Stakeholders
Active stakeholder engagement—through interviews, surveys, or workshops—helps validate the relevance of the identified topics and gather external insights on risks and opportunities.
8. Build the Materiality Matrix and Prioritize Topics
The Double Materiality Matrix organizes identified topics according to their financial and impact relevance. This allows the company to strategically prioritize the most critical topics for both the business and its stakeholders.
9. Conduct Strategic Analysis
The prioritized topics should be analyzed within the company’s strategic context, considering:
- Long-term risks and opportunities
- Alignment with corporate objectives
- Potential regulatory implications
10. Validate Material Topics and Finalize the List
The final validation of material topics should involve senior leadership, ensuring that the analysis reflects the company’s strategic vision and can be incorporated into decision-making and sustainability reporting.
Double Materiality Spreadsheet: A Practical Tool to Streamline the Process
To simplify the application of Double Materiality, we have developed a structured spreadsheet that helps map impacts, prioritize topics, and build the materiality matrix.
This tool allows for a clear organization of information, ensuring an objective analysis aligned with best practices and regulatory requirements. With it, your company can conduct a more efficient process, engage stakeholders, and consolidate strategic insights for decision-making.
The best part? It is 100% aligned with ABNT PR 2030-2! Take a look at its structure:
Why Is Double Materiality an Irreversible Path?
Double Materiality is not just a regulatory trend—it represents a structural shift in how companies are assessed and how they must operate in an increasingly interconnected world, where sustainable practices are a top priority.
Investors, consumers, and regulators now demand that organizations not only report their financial risks but also take responsibility for their social and environmental impacts.
Ignoring this new approach poses serious risks:
- Loss of competitiveness
- Regulatory barriers
- Damage to corporate reputation
On the other hand, companies that strategically adopt Double Materiality benefit from:
- Greater credibility
- Attracting sustainable investments
- Strengthened resilience in the face of crises and market transformations
This is an irreversible path for organizations that want to remain relevant and prepared for future challenges and opportunities.


